Business Name: BeeHive Homes of Plainview
Address: 1435 Lometa Dr, Plainview, TX 79072
Phone: (806) 452-5883
BeeHive Homes of Plainview
Beehive Homes of Plainview assisted living care is ideal for those who value their independence but require help with some of the activities of daily living. Residents enjoy 24-hour support, private bedrooms with baths, medication monitoring, home-cooked meals, housekeeping and laundry services, social activities and outings, and daily physical and mental exercise opportunities. Beehive Homes memory care services accommodates the growing number of seniors affected by memory loss and dementia. Beehive Homes offers respite (short-term) care for your loved one should the need arise. Whether help is needed after a surgery or illness, for vacation coverage, or just a break from the routine, respite care provides you peace of mind for any length of stay.
1435 Lometa Dr, Plainview, TX 79072
Business Hours
Monday thru Sunday: 9:00am to 5:00pm
Facebook: https://www.facebook.com/BeeHivePV
YouTube: https://www.youtube.com/@WelcomeHomeBeeHiveHomes
Families hardly ever budget for the day a parent requires help with bathing or begins to forget the stove. It feels abrupt, even when the indications were there for years. I have sat at kitchen tables with sons who deal with spreadsheets for a living and daughters who kept every invoice in a shoebox, all staring at the exact same question: how do we spend for assisted living or memory care without dismantling whatever our parents constructed? The answer is part math, part worths, and part timing. It needs honest conversations, a clear stock of resources, and the discipline to compare care models with both heart and calculator in hand.
What care actually costs - and why it varies so much
When people say "assisted living," they often visualize a neat apartment or condo, a dining-room with options, and a nurse down the hall. What they don't see is the rates complexity. Base rates and care costs function like airline tickets: comparable seats, very different prices depending upon need, services, and timing.
Across the United States, assisted living base leas commonly range from 3,000 to 6,000 dollars per month. That base rate generally covers a personal or semi-private apartment or condo, energies, meals, activities, and light housekeeping. The fork in the road is the care plan. Aid with medications, showering, dressing, and movement typically adds tiered charges. For someone needing one to 2 "activities of daily living" (ADLs), include 500 to 1,500 dollars. For more extensive support, the care element can reach 2,500 dollars or more. Falls, diabetes management, incontinence, and night-time roaming tend to increase costs due to the fact that they require more staffing and scientific oversight.
Memory care is generally more expensive, since the environment is protected and staffed for cognitive impairment. Typical all-in costs run 5,500 to 9,000 dollars per month, often higher in significant metro areas. The higher rate reflects smaller sized staff-to-resident ratios, specialized programs, and security innovation. A resident who wanders, sundowns, or withstands care needs foreseeable staffing, not simply kind intentions.
Respite care lands somewhere in between. Neighborhoods frequently offer provided apartments for short stays, priced daily or each week. Expect 150 to 350 dollars daily for assisted living respite, and 200 to 400 dollars daily for memory care respite, depending upon location and level of care. This can be a wise bridge when a household caretaker needs a break, a home is being remodelled to accommodate safety changes, or you are evaluating fit before a longer commitment.
Costs differ for real factors. A rural community near a major health center and with tenured personnel will be costlier than a rural option with greater turnover. A newer structure with personal verandas and a restaurant charges more than a modest, older home with shared spaces. None of this always forecasts quality of care, however it does influence the monthly expense. Exploring three places within the very same zip code can still produce a 1,500 dollar spread.
Start with the genuine concern: what does your parent requirement now, and what will likely change
Before crunching numbers, examine care needs with uniqueness. Two cases that look comparable on paper can diverge rapidly in practice. A father with mild amnesia who is calm and social might do effectively in assisted living with medication management and cueing. A mother with vascular dementia who ends up being distressed at dusk and attempts to leave the building after dinner will be safer in memory care, even if she appears physically stronger.
A primary care doctor or geriatrician can complete a practical assessment. A lot of neighborhoods will likewise do their own evaluation before approval. Ask them to map current needs and likely progression over the next 12 to 24 months. Parkinson's disease and numerous dementias follow familiar arcs. If a relocate to memory care seems likely within a year or more, put numbers to that now. The worst monetary surprises come when families budget plan for the least expensive scenario and then greater care requirements arrive with urgency.
I dealt with a household who found a lovely assisted living choice at 4,200 dollars a month, with an approximated care plan of 800 dollars. Within 9 months, the resident's diabetes destabilized, causing more frequent tracking and a higher-tier insulin management program. The care plan leapt to 1,900 dollars. The total still made good sense, however since the adult children expected a flatter expense curve, it shook their spending plan. Excellent planning isn't about forecasting the impossible. It has to do with acknowledging the range.
Build a clean monetary photo before you tour anything
When I ask families for assisted living a financial photo, lots of reach for the most recent bank statement. That is just one piece. Construct a clear, present view and compose it down so everyone sees the exact same numbers.
- Monthly income: Social Security, pensions, annuities, required minimum distributions, and any rental income. Note net quantities, not gross. Liquid properties: monitoring, savings, cash market funds, brokerage accounts, CDs, money worth of life insurance. Identify which properties can be tapped without charges and in what order. Non-liquid possessions: the home, a trip residential or commercial property, a small business interest, and any asset that might need time to sell or lease. Benefits and policies: long-term care insurance (benefit triggers, daily maximum, elimination period, policy cap), VA benefits eligibility, and any employer retired person benefits. Liabilities: home loan, home equity loans, charge card, medical debt. Understanding obligations matters when picking between renting, offering, or borrowing against the home.
This is list one of 2. Keep it short and accurate. If one brother or sister handles Mom's money and another doesn't understand the accounts, start here to eliminate mystery and resentment.
With the snapshot in hand, produce an easy monthly capital. If Mom's earnings amounts to 3,200 dollars monthly and her most likely assisted living expenditure is 5,500 dollars, you can see a 2,300 dollar regular monthly gap. Multiply by 12 to get the annual draw, then consider for how long existing properties can sustain that draw assuming modest portfolio growth. Lots of households use a conservative 3 to 4 percent net return for planning, although actual returns will vary.
Understand what Medicare and Medicaid cover, and what they do n'thtmlplcehlder 44end. A severe surprise for lots of: Medicare does not pay for assisted living or memory care room and board. Medicare covers medical services, not custodial care. It will pay for hospitalizations, doctor visits, certain therapies, and limited home health under rigorous requirements. It may cover hospice services supplied within a senior living neighborhood. It will not pay the monthly rent. Medicaid, by contrast, can cover some long-term care costs for those who meet medical and monetary eligibility. Medicaid is state-administered, and protection guidelines differ extensively. Some states use Medicaid waivers for assisted living or memory care, typically with waitlists and limited supplier networks. Others assign more funding to nursing homes. If you think Medicaid might be part of the strategy, speak early with an elder law attorney who understands your state's guidelines on asset limits, earnings caps, and look-back periods for transfers. Preparation ahead can maintain alternatives. Waiting up until funds are depleted can restrict options to neighborhoods with readily available Medicaid beds, which may not be where you want your parent to live. The Veterans Administration is another possible resource. The Help and Participation pension can supplement earnings for eligible veterans and surviving spouses who require help with day-to-day activities. Advantage amounts differ based upon reliance, income, and possessions, and the application needs comprehensive paperwork. I have seen families leave thousands on the table due to the fact that no one knew to pursue it. Long-term care insurance: read the policy, not the brochure
If your parent owns long-term care insurance, the policy details matter more than the premium history. Every policy has triggers, limitations, and exclusions.
Most policies require that a certified professional accredit the insured needs aid with 2 or more ADLs or needs supervision due to cognitive problems. The elimination period functions like a deductible determined in days, often 30 to 90. Some policies count calendar days after benefit triggers are fulfilled, others count just days when paid care is supplied. If your elimination duration is based on service days and you only receive care 3 days a week, the clock moves slowly.
Daily or month-to-month optimums cap just how much the insurance company pays. If the policy pays up to 200 dollars per day and the neighborhood costs 240 daily, you are responsible for the difference. Life time maximums or pools of cash set the ceiling. Inflation riders, if included, can assist policies composed decades ago stay beneficial, but advantages may still lag existing costs in high-priced markets.
Call the insurance company, request an advantages summary, and ask how claims are initiated for assisted living or memory care. Neighborhoods with knowledgeable business offices can help with the documentation. Households who prepare to "save the policy for later" often discover that later showed up 2 years previously than they understood. If the policy has a minimal pool, you might utilize it during the highest-cost years, which for many are in memory care instead of early assisted living.
The home: offer, rent, obtain, or keep
For lots of older grownups, the home is the largest property. What to do with it is both monetary and emotional. There is no universal right answer.
Selling the home can money numerous years of senior living costs, specifically if equity is strong and the residential or commercial property requires pricey upkeep. Families frequently hesitate due to the fact that selling seems like a final action. Look out for market timing. If your house requires repairs to command a great cost, weigh the cost and time against the carrying expenses of waiting. I have seen households invest 30,000 dollars on upgrades that returned 20,000 in list price due to the fact that they were refurbishing to their own taste instead of to purchaser expectations.
Renting the home can produce income and buy time. Run a sober pro forma. Subtract property taxes, insurance coverage, management costs, upkeep, and anticipated vacancies from the gross lease. A 3,000 dollar month-to-month lease that nets 1,800 after expenses might still be rewarding, specifically if offering sets off a big capital gain or if there is a desire to keep the home in the household. Keep in mind, rental income counts in Medicaid eligibility computations. If Medicaid is in the image, consult with counsel.
Borrowing versus the home through a home equity credit line or a reverse mortgage can bridge a deficiency. A reverse home loan, when used properly, can provide tax-free cash flow and keep the property owner in location for a time, and in some cases, fund assisted living after leaving if the partner remains in the home. But the charges are real, and as soon as the customer completely leaves the home, the loan ends up being due. Reverse mortgages can be a clever tool for specific scenarios, especially for couples when one partner stays at home and the other relocations into care. They are not a cure-all.
Keeping the home in the family typically works finest when a child means to live in it and can buy out siblings at a reasonable rate, or when there is a strong nostalgic factor and the carrying costs are manageable. If you decide to keep it, deal with the house like an investment, not a shrine. Budget plan for roofing, A/C, and aging facilities, not simply lawn care.
Taxes matter more than individuals expect
Two families can invest the same on senior living and end up with very various after-tax outcomes. A couple of points to see:
- Medical cost reductions: A considerable part of assisted living or memory care costs might be tax deductible if the resident is thought about chronically ill and care is supplied under a plan of care by a licensed professional. Memory care costs typically certify at a greater percentage since supervision for cognitive problems is part of the medical requirement. Speak with a tax expert. Keep detailed billings that separate lease from care. Capital gains: Offering appreciated financial investments or a 2nd home to fund care sets off gains. Timing matters. Spreading sales over fiscal year, collecting losses, or collaborating with needed minimum circulations can soften the tax hit. Basis step-up: If one partner passes away while owning appreciated properties, the surviving partner may receive a step-up in basis. That can change whether you offer the home now or later. This is where an elder law lawyer and a certified public accountant earn their keep. State taxes: Transferring to a neighborhood across state lines can change tax direct exposure. Some states tax Social Security, others do not. Combine this with distance to family and health care when selecting a location.
This is the unglamorous part of preparation, but every dollar you keep from unneeded taxes is a dollar that pays for care or preserves alternatives later.
Compare communities the method a CFO would, with tenderness
I like a good tour. The lobby smells like cookies, and the activity calendar is excellent. Still, the monetary file is as essential as the features. Request for the fee schedule in writing, consisting of how and when care charges alter. Some neighborhoods utilize service indicate price care, others utilize tiers. Understand which services fall under which tier. Ask how typically care levels are reassessed and just how much notice you get before fees change.
Ask about yearly rent boosts. Typical boosts fall between 3 and 8 percent. I have seen unique evaluations for major renovations. If a community is part of a bigger company, pull public evaluations with a crucial eye. Not every negative review is reasonable, but patterns matter, specifically around billing practices and staffing consistency.
Memory care need to come with training and staffing ratios that align with your loved one's requirements. A resident who is a flight danger needs doors, not assures. Wander-guard systems prevent catastrophes, however they likewise cost cash and require attentive personnel. If you anticipate to count on respite care periodically, ask about schedule and prices now. Many neighborhoods focus on respite during slower seasons and limit it when occupancy is high.
Finally, do a simple tension test. If the community raises rates by 5 percent next year and the year after, can your strategy absorb it? If care requirements jump a tier, what happens to your month-to-month gap? Strategies ought to endure a couple of unwelcome surprises without collapsing.
Bringing household into the strategy without blowing it up
Money and caregiving draw out old household characteristics. Clarity assists. Share the financial picture with the person who holds the durable power of lawyer and any brother or sisters associated with decision-making. If one family member supplies the majority of hands-on care in the house, factor that into how resources are used and how decisions are made. I have actually watched relationships fray when an exhausted caregiver feels unnoticeable while out-of-town brother or sisters push to postpone a move for cost reasons.
If you are thinking about private caretakers in the house as an alternative or a bridge, cost it honestly. Twelve hours a day at 30 dollars per hour is approximately 10,800 dollars each month, not consisting of employer taxes if you hire directly. Overnight needs frequently press households into 24-hour protection, which can quickly go beyond 18,000 dollars per month. Assisted living or memory care is not immediately more affordable, however it typically is more predictable.
Use respite care strategically
Respite care is more than a breather. It can be a financial reconnaissance objective. A two-week respite stay lets you observe staffing, food, responsiveness, and culture without a year-long dedication. It also offers the community a chance to know your parent. If the team sees that your father grows in activities or your mother requires more hints than you realized, you will get a clearer picture of the real care level. Numerous communities will credit some part of respite fees toward the neighborhood cost if you select to move in, which softens duplication.
Families often utilize respite to line up the timing of a home sale, to produce breathing space throughout post-hospital rehab, or to test memory look after a spouse who insists they "do not require it." These are smart uses of brief stays. Utilized moderately but tactically, respite care can avoid rushed choices and prevent expensive missteps.
Sequence matters: the order in which you utilize resources can protect options
Think like a chess player. The first relocation affects the fifth.
- Unlock advantages early: If long-lasting care insurance coverage exists, initiate the claim when activates are satisfied rather than waiting. The removal period clock will not start till you do, and you don't recapture that time by delaying. Right-size the home choice: If offering the home is likely, prepare paperwork, clear clutter, and line up an agent before funds run thin. Better to offer with a 90-day runway than under pressure. Coordinate withdrawals: Usage taxable accounts for near-term needs when possible, while handling capital gains, then tap tax-deferred accounts as required minimum distributions start. Line up with the tax year. Use household aid intentionally: If adult kids are contributing funds, formalize it. Decide whether money is a gift or a loan, document it, and understand Medicaid ramifications if the parent later on applies. Build reserves: Keep three to 6 months of care costs in cash equivalents so short-term market swings don't require you to offer investments at a loss to satisfy regular monthly bills.
This is list 2 of 2. It shows patterns I have actually seen work repeatedly, not guidelines sculpted in stone.
Avoid the costly mistakes
A couple of mistakes show up over and over, frequently with big price tags.
Families in some cases put a parent based solely on a beautiful apartment without noticing that the care group turns over continuously. High turnover often implies irregular care and frequent re-assessments that ratchet charges. Do not be shy about asking for how long the administrator, nursing director, and memory care supervisor have actually been in place.

Another trap is the "we can handle in the house for simply a bit longer" technique without recalculating costs. If a primary caretaker collapses under the stress, you may face a medical facility stay, then a quick discharge, then an urgent placement at a community with immediate availability instead of best fit. Planned shifts generally cost less and feel less chaotic.

Families also ignore how quickly dementia advances after a medical crisis. A urinary system infection can cause delirium and an action down in function from which the person never ever totally rebounds. Budgeting ought to acknowledge that the mild slope can in some cases develop into a steeper hill.
Finally, beware of financial products you don't totally understand. I am not anti-annuity or anti-reverse home mortgage. Both can be suitable. But funding senior living is not the time for high-commission complexity unless it clearly resolves a defined issue and you have actually compared alternatives.
When the cash may not last
Sometimes the arithmetic states the funds will run out. That does not mean your parent is predestined for a poor result, however it does indicate you should prepare for that moment rather than hope it never arrives.
Ask neighborhoods, before move-in, whether they accept Medicaid after a personal pay duration, and if so, for how long that period must be. Some need 18 to 24 months of personal pay before they will think about transforming. Get this in composing. Others do decline Medicaid at all. In that case, you will need to plan for a relocation or make sure that alternative financing will be available.
If Medicaid is part of the long-term strategy, make certain possessions are entitled correctly, powers of attorney are existing, and records are spotless. Keep invoices and bank declarations. Inexplicable transfers raise flags. An excellent elder law attorney earns their cost here by lowering friction later.
Community-based Medicaid services, if readily available in your state, can be a bridge to keep somebody at home longer with at home aid. That can be a humane and cost-efficient path when suitable, especially for those not yet prepared for the structure of memory care.
Small choices that produce flexibility
People obsess over huge choices like selling your house and gloss over the small ones that compound. Going with a slightly smaller apartment or condo can shave 300 to 600 dollars per month without damaging quality of care. Bringing individual furnishings instead of buying new can protect money. Cancel subscriptions and insurance coverage that no longer fit. If your parent no longer drives, remove cars and truck expenses instead of leaving the car to depreciate and leak money.
Negotiate where it makes good sense. Communities are most likely to adjust neighborhood costs or offer a month free at financial year-end or when tenancy dips. If you are moving a couple into assisted living with one partner in memory care, inquire about bundled prices. It won't always work, however it often does.
Re-visit the plan two times a year. Needs shift, markets move, policies update, and family capacity changes. A thirty-minute check-in can catch a developing concern before it ends up being a crisis.
The human side of the ledger
Planning for senior living is finance wrapped around love. Numbers offer you options, however worths inform you which alternative to pick. Some parents will invest down to guarantee the calmer, safer environment of memory care. Others want to maintain a legacy for kids, accepting more modest environments. There is no wrong response if the individual at the center is appreciated and safe.
A child once told me, "I thought putting Mom in memory care implied I had actually failed her." 6 months later, she stated, "I got my relationship with her back." The line product that made that possible was not just the rent. It was the relief that allowed her to visit as a child instead of as an exhausted caregiver. That is not a number you can plug into a spreadsheet, yet it belongs in the calculation.
Good planning turns a frightening unidentified into a series of workable steps. Know what care levels expense and why. Stock earnings, assets, and benefits with clear eyes. Check out the long-term care policy carefully. Choose how to deal with the home with both heart and arithmetic. Bring taxes into the discussion early. Ask difficult questions on tours, and pressure-test your prepare for the likely bumps. If resources may run short, prepare paths that preserve dignity.
Assisted living, memory care, and respite care are not simply lines in a budget. They are tools to keep an older adult safe, engaged, and appreciated. With a working plan, you can focus less on the invoice and more on the individual you love. That is the genuine return on investment in senior care.
BeeHive Homes of Plainview provides assisted living care
BeeHive Homes of Plainview provides memory care services
BeeHive Homes of Plainview provides respite care services
BeeHive Homes of Plainview supports assistance with bathing and grooming
BeeHive Homes of Plainview offers private bedrooms with private bathrooms
BeeHive Homes of Plainview provides medication monitoring and documentation
BeeHive Homes of Plainview serves dietitian-approved meals
BeeHive Homes of Plainview provides housekeeping services
BeeHive Homes of Plainview provides laundry services
BeeHive Homes of Plainview offers community dining and social engagement activities
BeeHive Homes of Plainview features life enrichment activities
BeeHive Homes of Plainview supports personal care assistance during meals and daily routines
BeeHive Homes of Plainview promotes frequent physical and mental exercise opportunities
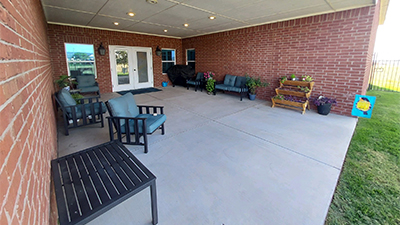
BeeHive Homes of Plainview provides a home-like residential environment
BeeHive Homes of Plainview creates customized care plans as residents’ needs change
BeeHive Homes of Plainview assesses individual resident care needs
BeeHive Homes of Plainview accepts private pay and long-term care insurance
BeeHive Homes of Plainview assists qualified veterans with Aid and Attendance benefits
BeeHive Homes of Plainview encourages meaningful resident-to-staff relationships
BeeHive Homes of Plainview delivers compassionate, attentive senior care focused on dignity and comfort
BeeHive Homes of Plainview has a phone number of (806) 452-5883
BeeHive Homes of Plainview has an address of 1435 Lometa Dr, Plainview, TX 79072
BeeHive Homes of Plainview has a website https://beehivehomes.com/locations/plainview/
BeeHive Homes of Plainview has Google Maps listing https://maps.app.goo.gl/UibVhBNmSuAjkgst5
BeeHive Homes of Plainview has Facebook page https://www.facebook.com/BeeHivePV
BeeHive Homes of Plainview has an YouTube page https://www.youtube.com/@WelcomeHomeBeeHiveHomes
BeeHive Homes of Plainview won Top Assisted Living Homes 2025
BeeHive Homes of Plainview earned Best Customer Service Award 2024
BeeHive Homes of Plainview placed 1st for Senior Living Communities 2025
People Also Ask about BeeHive Homes of Plainview
What is BeeHive Homes of Plainview Living monthly room rate?
The rate depends on the level of care that is needed. We do an initial evaluation for each potential resident to determine the level of care needed. The monthly rate is based on this evaluation. There are no hidden costs or fees
Can residents stay in BeeHive Homes until the end of their life?
Usually yes. There are exceptions, such as when there are safety issues with the resident, or they need 24 hour skilled nursing services
Do we have a nurse on staff?
No, but each BeeHive Home has a consulting Nurse available 24 – 7. if nursing services are needed, a doctor can order home health to come into the home
What are BeeHive Homes’ visiting hours?
Visiting hours are adjusted to accommodate the families and the resident’s needs… just not too early or too late
Do we have couple’s rooms available?
Yes, each home has rooms designed to accommodate couples. Please ask about the availability of these rooms
Where is BeeHive Homes of Plainview located?
BeeHive Homes of Plainview is conveniently located at 1435 Lometa Dr, Plainview, TX 79072. You can easily find directions on Google Maps or call at (806) 452-5883 Monday through Sunday 9:00am to 5:00pm
How can I contact BeeHive Homes of Plainview?
You can contact BeeHive Homes of Plainview by phone at: (806) 452-5883, visit their website at https://beehivehomes.com/locations/plainview/, or connect on social media via Facebook or YouTube
Door Red offers a familiar, easy-to-navigate dining option ideal for assisted living, memory care, senior care, elderly care, and respite care visits.